Casinos That Accept Wire Transfers in the UK
Bank-transfer labels and processes vary by casino, so availability, limits, withdrawals and fees need checking separately.
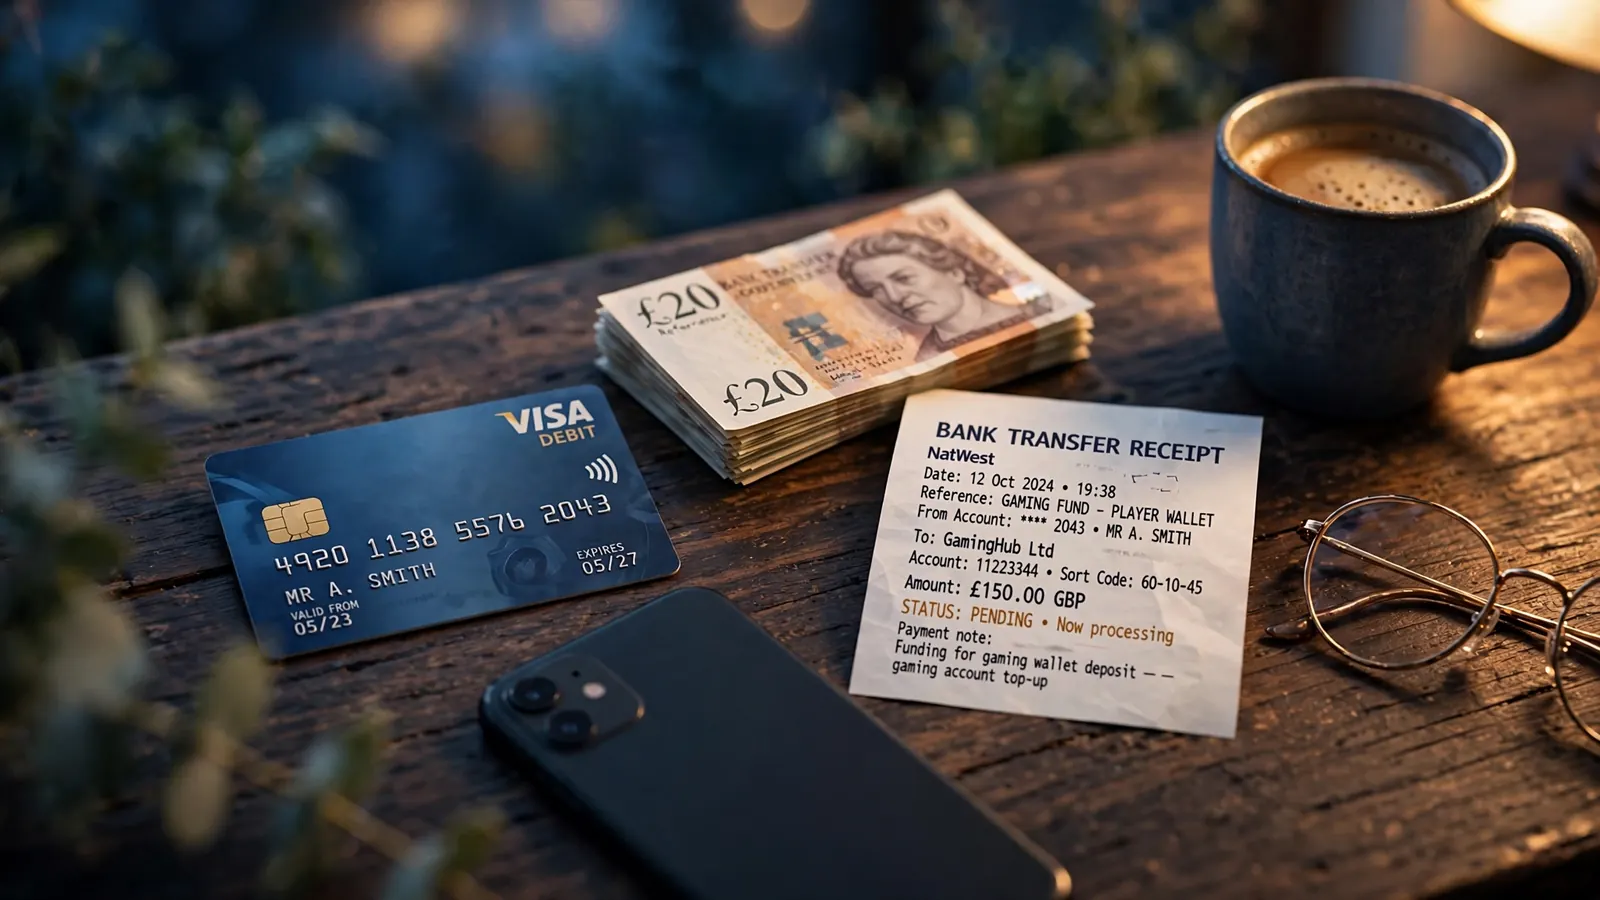
Table of Contents
- How Bank Transfers Fit into UK Casino Payments
- Checking Whether a Casino Supports Bank Transfers
- Bank Transfers for Online Casino Deposits
- Deposit Amounts and Payment Limits
- Keeping Payment Details Consistent
- Receiving Casino Winnings by Bank Transfer
- Bank Transfer Withdrawal Timing
- Fees and Currency Conversion
- UKGC Rules and Bank Transfer Payments
- Assessing a Bank Transfer Casino
How Bank Transfers Fit into UK Casino Payments
Bank transfer is one way to move money between a personal bank account and a casino account. In the phrase “wire transfer”, wire refers broadly to a bank-to-bank movement of funds; UK casino payment menus may use different labels for transfer-based services. The wording alone does not establish which process a particular site supports. A bank transfer should therefore be understood as a payment category, not as a guarantee that every casino offers the same route or process.
This category sits alongside card payments and e-wallets, but it is not interchangeable with either. A debit card uses the card-payment system and is linked to a bank account; the transaction is not, for that reason alone, a bank transfer. UK casinos commonly accept debit cards, including Visa and Mastercard, although the available card products still depend on the casino’s cashier. Credit-card payments for gambling are prohibited at UK-licensed casinos, a rule that has been in force since 14 April 2020.
An e-wallet is a separate payment service rather than a direct bank transfer. PayPal, Skrill and Neteller are examples of named wallet services, while Paysafecard is a prepaid voucher and is deposit-only. These distinctions matter because a casino may group several methods under a general heading such as “banking” or “payments”, even though their underlying routes differ. The label shown at the payment stage is more informative than a broad description of the site’s payment options.
UK Casinos That Accept E-Wallets: Payment Guide
Open banking can also form part of a transfer-based payment route. It permits a customer-authorised connection between financial services, but the name does not mean that every transaction follows an identical path. A specialist casino-payment review has reported that open banking and bank transfers can support instant deposits and fast withdrawals at many sites. That is a report about availability and potential speed, not a guarantee that a particular casino will offer those features or that every transaction will be immediate. The actual route and its operation are specific to the service presented by the casino.
Bank transfer can be relevant to both money entering a casino account and winnings leaving it, but those are distinct stages. A payment method’s presence in a general list does not by itself establish that it can be used in both directions. Nor does the word “transfer” reveal whether the casino uses a conventional bank payment, an open-banking connection, or another provider-mediated process. Those details belong to the individual payment option rather than to the general term.
The broader payment landscape includes methods with different roles. Debit cards provide a card-based route; e-wallets hold or route funds through a separate service; prepaid vouchers are designed for deposits rather than withdrawals. Bank transfers belong to a bank-account-based category, although the interface and provider can affect how the transaction is initiated. Treating all of these as equivalent because they appear in the same cashier would obscure differences in their function and eligibility.
Casinos That Accept Tether in the UK: Payments
For UK-facing gambling, payment choices exist within a regulated setting. Remote gambling licensees serving Great Britain consumers must hold the relevant UK Gambling Commission licence, and credit-card payments for gambling are not permitted. These rules shape the available payment environment, but they do not make bank transfer a universal feature of licensed casinos. A site’s regulatory status and the particular methods displayed for an account are separate matters.
The expression “casino that accepts wire transfer” can therefore describe more than one practical arrangement. One site may present a bank transfer directly; another may provide an open-banking service; a third may use a payment provider to initiate the movement of funds. The shared feature is a connection to a bank account, not necessarily an identical user journey or transaction outcome. For that reason, the phrase is useful as a broad description, but insufficient as a precise account of how a given payment works.
Bank transfers form one part of the UK casino payment mix rather than a substitute for every other method. Their defining distinction is the bank-account route, in contrast with card processing, wallet services and deposit-only vouchers. Reports of instant deposits or fast withdrawals indicate what some transfer-based services may support, while the specific availability and operation remain tied to the casino and payment option in question.
Top online casinos in the UK
- EvoSpinBonus: 125% up to €2500 + 125 Free Spins · Payout speed: 1-3 business days
- SpinFormulaBonus: 550% Up To £15,000 + 550 FS · Payout speed: 1-3 business days
- BritsinoBonus: Welcome Package – Get your £2,200 + 2,000 FS · Payout speed: 1-3 business days
- NightWinBonus: £900 + 400 free spins · Payout speed: 1-3 business days
- NightLuckBonus: Welcome Pack + 805% Up To 6400€ + 280 FS · Payout speed: 1-3 business days
- ZombillionBonus: Welcome Pack 250% up to £4000 + 200 FS · Payout speed: 1-3 business days
- WinBeastBonus: €5000 + 500 FS + €650 Freebet · Payout speed: 1-3 business days
Checking Whether a Casino Supports Bank Transfers
A general payment-method description is not enough to establish that a particular account can use a bank transfer. Casino pages may present methods available across a brand or a wider group of sites, while the options shown in the cashier can depend on the specific service and account. The cashier is therefore the relevant place to confirm whether a bank-transfer route is available for the account in question.
The distinction matters when comparing bank wire transfer online casinos. A reference to “bank transfer” may describe a direct bank payment, an open-banking service, or another route connected to a bank account. These are not necessarily interchangeable. A payment logo or a broad list of accepted methods does not establish which route is offered, nor whether the route is enabled for a particular account. The method’s displayed name and instructions should be checked rather than inferred from general wording.
Casinos That Accept Giropay in the UK
Availability also needs to be considered separately for deposits and withdrawals. A method appearing as a way to add funds does not, by itself, establish that it can receive a payout. Conversely, a general mention of bank transfer does not confirm that both directions are supported. When a casino is described as an online casino with bank wire transfer, the description should be treated as incomplete unless it clarifies which transaction types the cashier supports. This is a question of compatibility, not a prediction of how quickly either transaction will be handled.
The cashier may also distinguish between bank-transfer options that sound similar. If more than one route is listed, the instructions can show whether the transaction is handled through a bank’s own transfer facility or through a named payment service. That difference can matter because availability is attached to the specific option presented, not to the broad idea of paying from a bank account. A general statement that a site accepts bank payments should not be taken as confirmation that every form of bank transfer is available.
Casinos That Accept Wirecard in the UK: What to Check
Account currency is another part of compatibility. A specialist review reports that GBP is supported, but that statement should not be treated as confirmation of the currency set for every account or payment route. The account’s selected currency should be checked before the first transaction. If the account and the transfer are denominated differently, a conversion may be involved; confirming the account currency first helps establish whether the payment route matches the account’s settings. The currency shown in general site information may not be sufficient to determine an individual account’s configuration.
A practical check is to compare three details in the cashier: the payment route’s exact label, whether it is offered for the intended transaction type, and the currency associated with the account. If one of these details is unclear, the casino’s payment information or customer support can be consulted before proceeding. This avoids treating a method listed in promotional or review material as though it were already confirmed for the account.
The same care applies when looking for UKGC-licensed bank transfer casinos. A licence and a payment method are separate facts: a casino’s regulatory status does not demonstrate that a particular bank-transfer option is available. Likewise, a site’s general payment list does not establish its licensing status. These details need to be assessed independently, with the cashier used to confirm payment compatibility and the regulator’s public register used to check licensing.
Checking Bank Transfer Compatibility
- Check the payment route’s exact label in the cashier
- Confirm the method is offered for the intended transaction type
- Verify the currency associated with the account
- Check the operator’s licensing status on the UKGC public register
Searches for the best wire transfer online casino in the UK may produce broad comparisons, but a ranking cannot settle whether a route is currently available to a specific account. Payment lists can become outdated, and the cashier may present a narrower set of options than an overview page. A useful comparison therefore records what the account itself can select, rather than relying solely on a site-wide list or a third-party description.
The result of these checks is a more precise answer than a simple yes or no. A casino may support bank transfers in some form while offering a particular route only for one transaction type, or showing an account currency that needs confirmation. The relevant question is not merely whether the site mentions bank transfer, but whether the cashier presents the required route for the intended use and whether the account currency is clear before the first transaction.
Bank Transfers for Online Casino Deposits
A bank transfer can fund a casino balance by moving money from a bank account, while an open-banking payment can initiate a bank payment through a connected service. Both involve a bank account, but the payment route and the steps shown during checkout may differ. The label “bank transfer” therefore does not, by itself, establish how quickly a deposit will appear.
Deposit timing is the relevant distinction. A conventional transfer may involve processing beyond the casino’s own cashier, whereas some open-banking routes are designed to confirm a payment promptly. A specialist casino-payment review reports that open banking and bank transfers can support instant deposits at many sites. That finding describes a possibility, not a guaranteed outcome for every operator, bank or transaction.
Casinos that accept Interac in the UK: what’s known
An instant deposit, in this context, means that funds become available in the casino account without a noticeable wait after the payment is authorised. The exact experience depends on the route offered and whether the transaction completes successfully. A payment that remains pending at the bank or payment service may not appear in the casino balance immediately. The cashier’s confirmation is therefore more informative than the method’s general label.
The distinction between a bank transfer and open banking matters because the names can be used broadly in payment menus. One option may direct a customer to approve a payment through a bank interface; another may ask for bank details or use a separate transfer process. The cashier’s instructions indicate which process applies. The timing reported for one route should not be assumed to apply to another merely because both draw on a bank account.
For a deposit, the sequence is broadly practical: select the bank-related option, follow the payment service’s instructions and check whether the casino balance updates. If the payment is authorised but the balance does not change, repeating it immediately could risk creating a duplicate transaction. The account and payment service should instead be checked for a pending or completed status before any further attempt.
A rapid balance update is useful for distinguishing payment availability from transaction speed. A casino may list a bank-related method while the specific route does not provide instant credit. Conversely, a site using open banking may offer an immediate deposit through that service. These outcomes cannot be inferred from the words “wire transfer” alone; the payment flow and its stated processing information are more relevant.
Deposit speed should also be kept separate from withdrawal speed. A service may make funds available quickly when paying into an account without setting the same expectation for money leaving it. The specialist review’s statement that such routes can also support fast withdrawals concerns a different transaction direction and does not establish that a casino deposit and a payout will take the same time.
Making a Deposit
Select the option
Choose the bank-related payment option in the casino cashier.
Follow instructions
Complete the payment following the specific instructions of the payment service.
Verify balance
Check whether the casino balance updates to confirm the deposit was successful.
The useful distinction is thus between the underlying source of funds and the payment process used to move them. Bank-account funding may be presented as a transfer or arranged through open banking, and some of those routes can credit deposits instantly. The timing remains specific to the service and transaction rather than an inherent property of every bank transfer. For an online casino deposit, the cashier’s method description and the status shown after authorisation provide the clearest indication of what has occurred.
Deposit Amounts and Payment Limits
The amount required to open a casino balance is not necessarily the same across payment methods. A specialist casino review reports minimum deposits in the £10–£20 range, with the applicable figure depending on the selected method. That range is a broad guide, not a fixed minimum for every account or a guarantee that a bank transfer will be accepted at either threshold.
For a casino wire transfer deposit, the minimum shown for the transfer route is the relevant starting point. A site may set a different entry amount for a bank payment than for a card or an e-wallet. The amount entered also has to meet any minimum imposed by the bank or payment service involved. Consequently, a figure quoted for one method should not be treated as a universal casino minimum.
Maximums are also method-dependent. A specialist casino review notes that deposit ceilings can differ by payment route and account status, and may apply separately to an individual transaction, a day or a month. These are distinct measures: a per-transaction cap limits one payment, while a daily or monthly cap concerns the total deposited within that period. A transfer amount below one threshold may still be affected by another.
Casinos that accept Entropay in the UK: what to check
This matters particularly where a larger sum is being considered. The fact that a casino accepts a bank transfer does not establish the maximum it will process, and an advertised ceiling for another payment method does not establish the transfer limit. The applicable amount can depend on the customer’s account status as well as the chosen route. Limits should therefore be understood as account- and method-specific rather than as a single figure for all casino deposits.
The practical distinction is between the casino’s minimum, the casino’s maximum and any separate restriction applied by the bank or transfer provider. A transaction has to fit the relevant requirements at each point. If a payment exceeds a casino-set cap, splitting it into smaller payments should not be assumed to remove any daily or monthly limit; those caps concern aggregated deposits as well as individual transactions.
For UK casino sites, the cashier is the useful place to establish the amount currently applicable to a selected deposit method. The displayed minimum and maximum can be checked before entering a payment, including whether the stated ceiling applies per transaction or across a period. Account-level restrictions may also affect the amount available. Where the cashier does not make the distinction clear, the operator’s payment terms can clarify how its limits are applied.
A low minimum does not imply a high maximum, and a generous transaction ceiling does not mean the same amount can be deposited repeatedly without regard to an aggregate cap. For wire transfer casino sites in the UK, the most reliable comparison is therefore not a general figure attached to the site, but the minimum and relevant maximum shown for the bank-transfer route and account in question.
Deposit Limits
Minimum deposits typically range from £10–£20, but the applicable figure depends on the selected method, account status, and any restrictions imposed by the bank or provider.
Keeping Payment Details Consistent
A bank transfer is easier to reconcile when the casino account and the bank account belong to the same person. Matching basic ownership details can reduce avoidable questions about who supplied the funds and whether a transaction is authorised. This does not remove the operator’s ability to carry out KYC or other checks, but it avoids creating a discrepancy through the payment route itself.
Consistency starts with the information recorded on the gambling account. A different name, spelling or personal detail across the casino profile and bank records may make it harder to establish that both accounts belong to one customer. The same applies when someone else’s bank account is used to fund a casino balance: even if the transfer is intended as a gift or informal arrangement, the payment can appear to come from a third party. That can prompt additional scrutiny or prevent the transaction from being handled as expected.
For a casino that accepts wire transfer deposits, the practical principle is therefore straightforward: use a bank account held in the same name as the casino account, and enter personal details accurately. A casino that accepts a bank wire transfer is not necessarily able to treat payments from any account as interchangeable. Its terms may set out ownership requirements, and those conditions can differ between operators. The cashier and payment terms are the relevant places to confirm them before making a transfer.
Casinos that accept WebMoney in the UK: what’s known
The same logic applies when a payment service sits between a bank and the casino. A route registered to another person, or one whose ownership cannot readily be connected with the casino profile, may complicate routine checks. A clean payment record is often built around one named account used consistently for both deposits and withdrawals. Where a particular route cannot be used in both directions, the operator’s stated process takes precedence; consistency does not override its payment rules.
This is also a security measure, not merely an administrative preference. Keeping control of the casino account and the funding account with the same person makes it less likely that a transaction will be mistaken for unauthorised activity. It also limits the need to explain why the account holder and the payment source appear to differ. No payment arrangement can guarantee that a transaction will avoid review, since operators may have separate checks, but aligned ownership details remove one preventable source of friction.
A shared household bank account can raise a different question from an account held solely by the casino customer. The fact that another person is known to the customer does not establish that the payment route meets the operator’s ownership conditions. The operator’s own rules determine whether such an account is acceptable. Where ownership is unclear, using it without checking may create a problem that a directly matched account would avoid.
Accordingly, the safest general approach is not to borrow another person’s bank details or use a payment account registered under a different name. Accurate, consistent account information supports clearer transaction records and reduces avoidable ownership queries, while leaving the casino’s security and verification procedures intact.
Do
- Use a bank account held in the same name as the casino account
- Enter personal details accurately to match bank records
Don’t
- Use another person’s bank details to fund the balance
- Use a payment account registered under a different name
Receiving Casino Winnings by Bank Transfer
When a casino account has been funded by bank transfer, winnings may be returned to the same bank account as part of the operator’s closed-loop payment controls. UK anti-money laundering rules generally require payouts to go back to the original payment source. The destination is therefore not always a matter of preference: the route used to deposit can shape how a later payout is handled.
This arrangement also serves an anti-fraud purpose. Returning funds to the source used to fund the account helps an operator check that money is moving between accounts associated with the same customer, rather than being redirected to an unrelated person. It is one reason a casino may decline a request to send winnings to a different bank account or payment method, even if the alternative appears more convenient.
The precise route depends on how the original payment was recorded. A bank transfer may be linked to particular account details, while a casino’s cashier may identify another payment service as the source of funds. If several methods have been used, the operator may need to apply its own payment rules alongside anti-money laundering requirements. A general statement that a casino accepts bank transfers does not, by itself, establish where every withdrawal will be sent.
An alternative destination can involve additional verification. For instance, a request to receive funds through a different route may prompt checks that establish the account holder’s identity or ownership of the proposed payment account. These checks do not necessarily mean that the request will be accepted; the casino must still follow its payment and compliance procedures. The applicable rules should be checked in the cashier and withdrawal terms, rather than inferred from the deposit options alone.
For casino winnings by wire transfer, the relevant distinction is between a payout being sent to the original bank source and a payout being redirected elsewhere. Where the bank account was the deposit source, returning the money there is consistent with the common source-return approach. Where another method funded the account, the casino may apply a different route or request further evidence before considering an alternative.
Payment details should therefore be understood as part of the withdrawal arrangement, not merely as a way to add funds. Before making a deposit, it is useful to establish whether the casino’s stated bank-transfer option is also the route it uses for returning funds. The central point is that the original source is commonly preferred for compliance and fraud prevention, while a change of destination can bring extra checks.
Bank Transfer Withdrawal Timing
The time taken for a bank-transfer withdrawal has two separate parts: the casino’s handling of the request and the bank transfer’s journey after it has been released. A displayed processing estimate may cover one part, both parts, or only a stated business-day window, so its meaning depends on the operator’s terms.
A specialist casino-payment review notes that the casino must approve a withdrawal before the transfer can be sent. That internal stage may take longer on a first withdrawal if KYC checks are still being completed. The review does not establish a standard approval period across operators. Consequently, the time shown by one casino should not be treated as a reliable forecast for another.
After approval, the payment enters the banking system. A separate specialist review identifies the sending bank’s cut-off times, weekends and currency conversion as factors that can affect delivery. A request approved late in the day may therefore not move through the same processing cycle as one released earlier. A weekend can also interrupt normal banking handling, while conversion between currencies may add another step.
Credit Card Ban
Credit-card payments for gambling are prohibited at UK-licensed casinos; bank transfers should not be used to bypass these restrictions.
These stages matter when interpreting phrases such as “fast withdrawal”. They may refer to the casino’s approval, the bank’s receipt of the instruction, or the point when funds appear in the account. Unless an operator defines the measure, the phrase does not identify which stage is being timed. A casino may process a request promptly while the transfer itself remains in progress.
For a wire-transfer casino withdrawal, the relevant terms should therefore be read for both the operator’s processing window and any description of bank delivery. It is also useful to distinguish calendar time from business-day handling where the operator specifies this; the available evidence does not support a single duration that applies across UK casinos or banks. If a payment appears delayed, the casino’s status update can clarify whether approval is pending or the transfer has already been issued. Those are different points in the process, and only the latter indicates that the bank transfer has begun.
Fees and Currency Conversion
The cost of a wire transfer payment at a casino may involve more than a charge shown by the operator. A specialist casino-payment review identifies several possible sources: a casino fee, a payment-provider charge, a fee from the sending or receiving bank, an exchange-rate spread, and, where relevant, network costs. Which of these applies depends on the payment route and the currencies involved; a charge should not be assumed simply because the method is a bank transfer.
Currency conversion can make the overall cost less visible. If the casino account and the bank account use different currencies, the conversion rate applied to the transaction matters as well as any stated flat fee. A specialist review notes that the exchange-rate spread can outweigh a visible fixed charge. The spread is the difference between the rate used for the conversion and a reference rate; it may be embedded in the amount converted rather than itemised as a separate payment fee.
The displayed casino balance is therefore not, by itself, enough to establish the full cost. The relevant comparison includes the amount debited by the bank, the amount credited to the casino account, and any charges disclosed by the operator or payment provider. A bank or card issuer may also impose its own fee, independently of the casino’s cashier terms. For a transfer involving conversion, the rate and the currency in which the final account is held can affect the total paid.
There is no single payment method that can be identified as the cheapest in every case. A specialist payment review recommends comparing the casino’s charge, provider and bank fees, currency spread, and any network cost for the specific amount and route being considered. A method with no visible casino fee may still carry an external charge or a less favourable conversion rate; conversely, a stated fee does not alone establish that the method is more expensive overall.
For a wire transfer, the useful comparison is consequently the total cost across the whole payment path, not the label attached to one line in the cashier. Where the account currency differs from the currency sent, conversion terms should be considered alongside explicit fees before the transaction is made.
UKGC Rules and Bank Transfer Payments
A bank wire transfer does not change the regulatory status of a casino. Remote gambling licensees serving customers in Great Britain must hold the relevant UK Gambling Commission (UKGC) licence, whether they are based in the UK or elsewhere. Online gambling is legal in the UK only through licensed and regulated sites; the Gambling Act 2005 applies in England, Wales and Scotland, but not Northern Ireland.
Casinos That Accept Bitcoin in the UK: What to Check
The rules concern the operator and its handling of gambling activity, not just the payment channel. A casino cannot avoid its obligations by accepting deposits through a bank rather than a card or e-wallet. Before a new customer makes a first deposit, the operator must prompt them to set a financial limit. It must also make account-level limit controls accessible, so limits can be managed through the account rather than treated as a one-off payment setting.
Age checks are also required before an operator allows a customer to deposit. The legal minimum age for online gambling with a UKGC-licensed operator is 18. These requirements apply regardless of whether a deposit is described as a bank transfer, bank wire or another payment method.
The credit-card restriction is another part of the payment framework. The regulator prohibited credit-card payments for gambling on 14 April 2020, and that ban remains in force. Remote operators must not accept credit-card payments for gambling, including where a credit card is routed through a money service business. They also cannot accept wallet payments where the wallet permits credit-card funds to be used for gambling. A bank transfer should therefore not be treated as a way to bypass restrictions on prohibited funding sources.
For a UKGC casino bank transfer, the relevant regulatory question is not simply whether the cashier displays a wire option. The operator must still meet its wider obligations as a remote gambling licensee. These include providing responsible-gambling protections, an internal complaints process and access to an approved Alternative Dispute Resolution service. Operators are also required to contribute to the Research, Education and Treatment levy.
A payment method alone cannot establish that a casino is properly authorised. The licence applies to the operator, while the transfer is only one part of the transaction. The regulatory framework therefore remains the same when a customer funds an account by bank transfer.
Assessing a Bank Transfer Casino
A sound comparison of UK casinos that accept bank transfers should begin with whether the payment route suits the intended use, rather than with a general claim that one site is “best”. The cashier should identify the available bank-transfer option, and the operator’s current UK Gambling Commission licence should be checked on the public register before depositing. Payment availability alone does not establish that a casino is suitable.
Speed claims need careful interpretation. A specialist casino review reports that open banking and bank transfers can support instant deposits and fast withdrawals at many sites. This is a possibility, not a service standard applying to every casino or transaction. Any stated processing estimate should be read alongside the operator’s terms, since deposit confirmation and withdrawal handling are distinct parts of the experience.
Cost is another comparison point, but no payment route can be treated as universally cheapest. Payment-cost reviews identify several possible charges: those imposed by the casino, the payment provider, a bank or issuer, and, where relevant, a network. Currency conversion can also affect the final amount through an exchange-rate spread. Comparisons therefore need to reflect the same transaction amount and account currency; a visible fixed charge alone may not show the full cost.
A practical assessment records the details that can be verified: the named transfer route, any casino or provider charge, the account currency, and the stated timing for deposits and withdrawals. It also distinguishes information shown in the cashier from broader claims made in promotional material. Where a review describes a method as fast or low-cost without specifying the conditions, that description is weak evidence for an individual account.
The result is not a universal ranking. It is a comparison of concrete terms and of how clearly the casino explains them. A site with a suitable transfer option, transparent charges and a valid UKGC licence can be assessed on those grounds without treating speed or cost claims as guarantees.
What is the fastest withdrawal method for UK casinos?
PayPal, open banking services and debit cards linked to fast payout systems are generally among the quickest options. The casino’s approval process and your verification status also affect how quickly funds arrive.
What is the current minimum deposit?
The minimum deposit usually starts at £10–£20, depending on the payment method.
Which method has the lowest fees?
There is no universal lowest-fee method. Compare casino and provider charges, bank or issuer fees, currency-conversion spreads and any network costs for the payment you plan to make.
Which payment methods are accepted in Great Britain?
UK casinos commonly accept Visa and Mastercard debit cards, and some offer bank transfers, open banking and e-wallets such as PayPal, Skrill or Neteller. The methods available for a particular account are shown in the casino’s cashier.
Are Visa and Mastercard deposits definitely debit cards?
No. Visa and Mastercard are commonly accepted as debit cards, but the eligible card product depends on the casino’s cashier. Credit-card gambling is prohibited at UK-licensed casinos.
Can I use a credit card at 333 Casino in Great Britain?
No. Credit-card payments for gambling are prohibited at UK-licensed casinos in Great Britain.
Created by the ”30bet” editorial team.